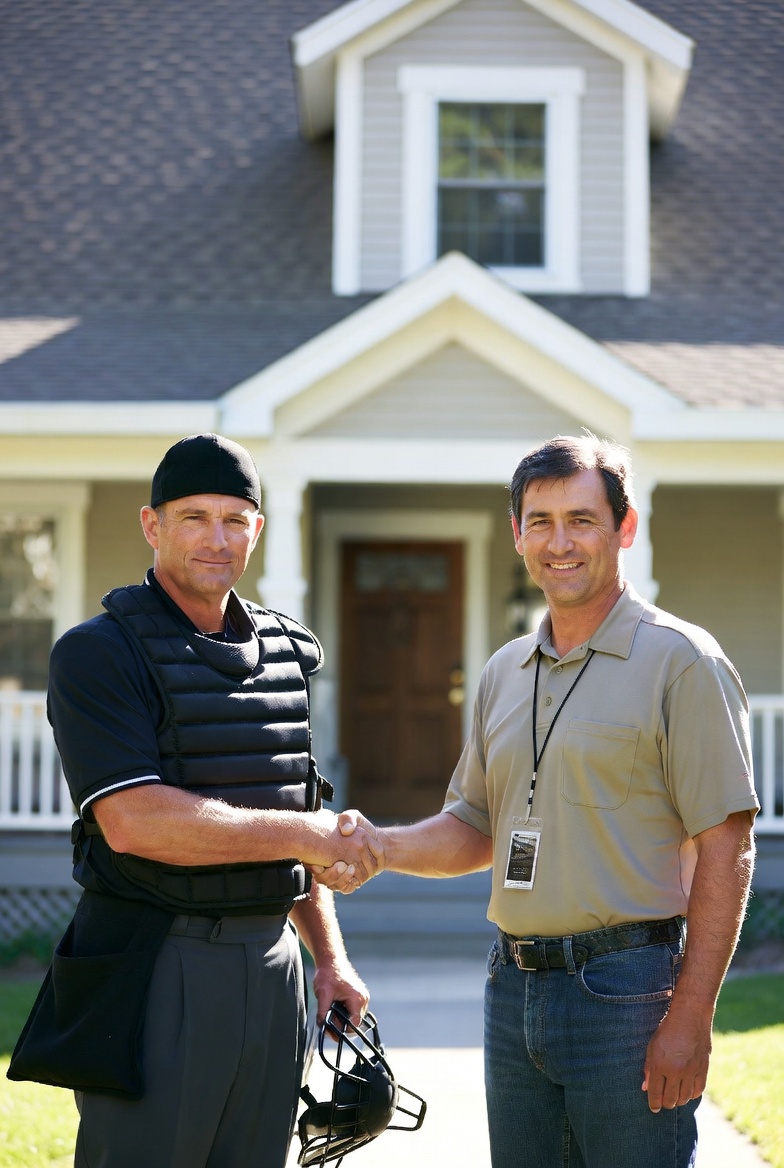
As a former pitcher for the Rays, I've lived this nightmare more times than I care to count: You battle through a full count, dig deep, and throw what you know is a filthy strike—knee-high, on the black. The catcher sets up perfectly, glove barely moves... and the umpire calls it a ball.
You worked as hard as you could, executed the pitch flawlessly, but one neutral call flips the inning. When you (or the catcher) politely ask, "Blue, where'd you see that?"—the response is often a glare and a sharp "Don't tell me how to do my job." The call stands. No debate. Momentum gone.
Sound familiar?
Swap the mound for a Texas home in Legacy West, Plano, or Frisco, and you've got the exact same frustration in real estate: the appraisal.
The appraiser is the umpire of the mortgage world—impartial, rule-bound, and their valuation is binding for the lender. Both enforce fairness without picking sides. But here's the kicker that frustrates buyers and sellers alike:
A pitcher can throw the perfect pitch, just to have the ump call it a ball.
And when challenged politely? Offense taken. Same with appraisers: Your agent submits strong comps, highlights upgrades, or points out a missed nearby sale in a Reconsideration of Value (ROV). Too often, the reply feels defensive: "If those were better comps, I'd have used them already." Or worse—silence. They get offended at the challenge, just like an ump who doesn't want his zone questioned.
The Parallels Are Uncanny
They're not exactly the same—umpires deal in real-time split-second judgments on a moving ball, while appraisers analyze data like square footage, comps, condition, location, and market trends. But the similarities are striking:
- Neutral officials: Neither roots for buyer, seller, lender, or team. They follow the book (MLB rules vs. USPAP standards).
- High-stakes calls: A blown strike can lose a game; a low appraisal can kill financing, force price drops, extra cash, or walking away—especially in competitive DFW markets.
- Defensive reactions to challenges: Politely questioning either often backfires. In baseball, arguing gets you ejected; in appraisals, push too hard and options narrow.
So What Can You Do When the Call Goes Against You?
Stay cool—it's not personal.
- Prep early: Get pre-approved, know realistic values.
- Provide evidence calmly: Submit better comps/photos via your lender for an ROV (direct contact to the appraiser usually isn't allowed).
- Have backups: Seller credits, rate buydowns, or program tweaks can save the deal. VA loans (huge for my military clients) offer extra flexibility.
In my pitching days, I couldn't control the ump—but I controlled my prep and mindset. Same here: Navigate appraisals like calling a great game.
The Bottom Line
Umpires and appraisers aren't one and the same, but their roles keep things honest—even when the call stings. A tough appraisal protects everyone from overpaying long-term.
If you're buying or refinancing in the DFW area and want to avoid surprises, let's talk. I treat clients like All-Stars: transparent guidance, quick rate checks, and strategies for whatever call comes.
Ready to Step Up?
- Apply online at bigleaguelender.com
- Book a free consult—no pressure
Let's turn your deal into a grand slam. ⚾🏠
Ever had a low appraisal (or bad ump call) derail things? Share in the comments!
Test Social Preview
Verify how this post appears when shared. These tools also force social platforms to refresh their cached preview.
Questions About This Topic?
Get personalized answers from our Sports & Entertainment Division specialists. Let's discuss your mortgage needs.